Collection efficiency formula: three versions, worked through
Collection efficiency = collections ÷ billing × 100. Current, monthly and cumulative versions worked through for NBFCs, and why a month can show 105%.
Contents 10 sections
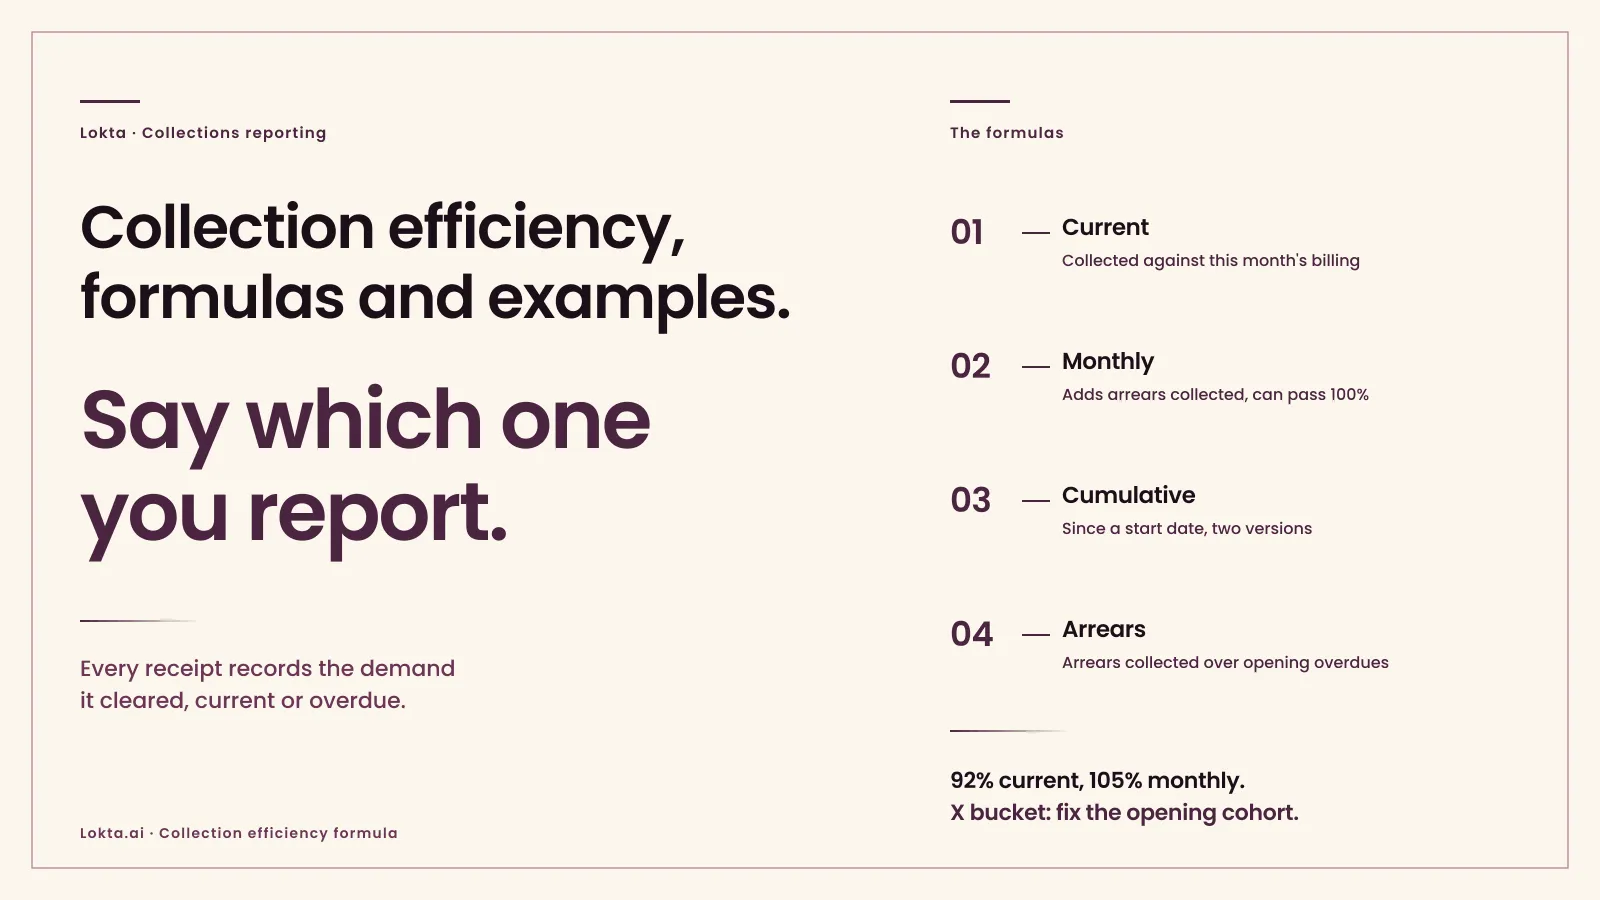
Collection efficiency (%) = collections ÷ billing × 100. Define the period and which dues each receipt cleared: lenders use at least three versions. Current collection efficiency counts only what was collected against this month’s instalments. Monthly collection efficiency adds overdue collections to the numerator and can pass 100%. Cumulative collection efficiency runs from a start date, sometimes with opening overdues in the denominator. Report which one you use, and never compare figures built on different formulas.
If you report collection efficiency to a board, a lender or a rating agency, a careful reader’s first question is which formula you used. Two NBFCs can both report 98% and be collecting very differently.
“Collections” and “billing” each have more than one reasonable meaning, and a monthly figure of 105% looks like a strong month whether or not it is one. The fix is to pick a formula, say which one, and produce it from the same loan records every month.
- Three formulas share one name. Current, monthly and cumulative collection efficiency divide different things.
- Above 100% is a formula effect, or a bug. Arrears in the numerator can push past 100 in a catch-up month. With advances excluded and periods aligned, arrears receipts must explain the excess.
- Write-offs and prepayments move the number. A higher ratio does not by itself show better payment of scheduled dues.
- Report two figures. Current collection efficiency beside the total tells the reader how much came from catching up.
- Every receipt needs a target. The loan system has to record which demand each rupee cleared.
What is collection efficiency?
It is the share of what borrowers owed in a period that the lender actually collected. The definitions differ in what counts as owed, what counts as collected, and over what period. ICRA prints the formula as a footnote in its securitisation rating reports, and a lender’s own reports can do the same.
Before it rates a pool, an agency also reads the loan-level data in the lender’s loan tape.
Which three formulas do lenders mix up?
ICRA’s June 2025 securitisation methodology lists current, monthly and cumulative measures. We use current here for receipts allocated to the month’s own demand, and monthly for current plus overdue receipts divided by that month’s billing. Keep the allocation rule beside the formula: the labels alone do not specify it completely.
| Measure | Numerator | Denominator | Can it pass 100%? |
|---|---|---|---|
| Current collection efficiency | Collections against this month’s instalments | This month’s billing | No |
| Monthly collection efficiency | Current and overdue receipts in the month, excluding advances in this example | This month’s billing | Yes |
| Cumulative collection efficiency | Current and overdue receipts since a start date | Billing since that date, with or without opening overdues | Can exceed 100% when opening arrears are collected but excluded from the denominator |
Use the same eligible components on both sides: principal, interest and any charges included in your report’s definition. A receipt outside those components should not inflate the numerator.
For backlog recovery, use arrears collection efficiency: overdue receipts in the month divided by opening overdues. That definition appears in ICRA’s superseded 2019 methodology. We use it here as a separate reporting measure, not a current regulatory rule.
For cumulative efficiency, check the transaction definition. The Keertana report divides by cumulative billing. The Satin report adds opening overdues to that denominator. Use the required definition for the pool rather than choosing whichever looks better.
How can collection efficiency pass 100%?
When older arrears count as receipts but the denominator contains only this month’s demand. The Veritas rating report defines its monthly measure using current and overdue collections against monthly billing.
Take an illustrative October book. These are made-up figures, with no advances, reversals or other adjustments:
| Input | Amount | Where it belongs |
|---|---|---|
| Instalments due in October | ₹10 crore | Current and monthly denominator |
| Receipts allocated to October’s dues | ₹9.2 crore | Current numerator; part of monthly numerator |
| Receipts against older arrears | ₹1.3 crore | Arrears numerator; part of monthly numerator |
| Arrears outstanding at opening | ₹4 crore | Arrears denominator |
₹9.2 crore ÷ ₹10 crore × 100. ₹0.8 crore of October’s own demand remains unpaid.
(₹9.2 crore + ₹1.3 crore) ÷ ₹10 crore × 100. Older arrears lift the headline above 100%.
₹1.3 crore ÷ ₹4 crore × 100. ₹2.7 crore of the opening backlog remains before other adjustments.
If October is the start of your cumulative window, the same receipts give 105% against billing alone: 10.5 ÷ 10 × 100. Including the ₹4 crore opening arrears gives 75%: 10.5 ÷ (10 + 4) × 100. State which denominator the report requires.
Collection efficiency explained: what a steady 97% can hide separates current dues, older recoveries and payments ahead. The video’s headline includes payments ahead. The 105% monthly example above includes current and overdue receipts only, so compare the definitions before comparing the percentages.
A 105% month can be good news: borrowers who fell behind are catching up. It can also mean the book carries a large pile of arrears that some borrowers are paying down, while 8% of this month’s billing went unpaid. The monthly figure alone cannot tell the two apart.
How do you calculate X-bucket collection efficiency?
For this article, X bucket means the fixed cohort of accounts that are current at the start of the reporting month. An account can be current after clearing earlier arrears, so cohort membership does not imply a clean lifetime payment history. What the X, 0, 1, 2 and 3 buckets mean, and how each is worked, is in the bucket-by-bucket collection strategy.
X-bucket collection efficiency (%) = receipts allocated during the month to that month’s demand for the opening-current cohort ÷ that cohort’s demand for the month × 100.
Suppose the cohort has ₹1,00,000 of demand and pays ₹92,000 against it during the month. X-bucket efficiency is 92%. A further ₹5,000 paid towards future dues stays outside this calculation. It doesn’t clear the ₹8,000 still unpaid against current demand.
Fix the membership at opening, including accounts that fall behind later in the month. Count partial payments only to the extent allocated to the cohort’s current demand. Net reversed receipts under the report’s declared date and cut-off, and exclude receipts from other cohorts. If the denominator is zero, report the ratio as not applicable.
Some reports use X and zero bucket differently. Print the cohort rule rather than assuming the labels match. The bucket strategy guide explains the opening-current convention and keeps it separate from DPD bands. This is a reporting definition, not an RBI classification.
Can a figure above 100% be a bug?
Yes, and the formula itself gives the check. With periods and eligible components aligned and advances excluded, overdue receipts must cover at least the amount above current billing. At 105% on ₹10 crore of billing, at least ₹0.5 crore must have come from arrears. If that split doesn’t reconcile, check the inputs and definition before circulating the report.
We met exactly that on BACO, the synthetic NBFC we run to test Lokta. A day-close briefing reported month-to-date collections of ₹8.27 crore against demand of ₹7.81 crore, or 105.9%, while showing nothing recovered from overdue and no account changing bucket. The numbers could not all be true. The data source had been briefly unreachable and the feature had fetched dummy data. The digital twin post tells the story. The lesson for a reporting team is to publish the overdue collections beside any figure above 100%, so the check is visible.
What else moves the number?
Write-offs change the demand included in a report. Prepayments add cash without necessarily clearing this month’s scheduled dues. Receipt dates and allocation rules also change the result, and so do mandate returns inside the month; see how to handle a NACH or UPI AutoPay bounce before the account rolls to the next bucket.
- Once an account is written off, its instalments leave the billing. ICRA’s securitisation methodology makes the point directly: a lender with a stricter write-off policy tends to show better collection efficiency than one that writes off less often.
- If prepayments and foreclosures count as collections, a month in which a block of loans closes early looks like a strong collections month.
- A payment made on the 30th but posted on the 1st counts in one month or the next, depending on whether the report uses value date or posting date.
- When a borrower pays less than the full amount due, the lender’s appropriation order decides whether the money clears current demand or older arrears, and so which formula it improves. The payment appropriation post works through how allocation rules change the result.
Which formula should you report?
Two figures side by side, each with its formula written out: current collection efficiency, and monthly or cumulative collection efficiency as your lenders or the transaction documents define it. Add arrears collection efficiency when overdues are material. State whether prepayments and written-off accounts are included.
For the collections team, the same measures cut by bucket are more useful than the book-wide figure. The X bucket, accounts that were current when the month began, is where a new miss shows up. Definitions vary between lenders, so print yours beside the number. Collection effort has a price too, and the cost to service a loan model shows where follow-up on overdue accounts sits in the per-loan figure. The bucket-by-bucket collection strategy post sets out what each bucket needs. Roll rate and cure rate show whether accounts in each bucket slide into a worse one or come back to current, and the collections KPIs post gives the formulas.
What does the loan system need to produce it?
Four things, recorded as events rather than rebuilt at month end:
- each instalment’s demand and due date, as it stood when it fell due
- each receipt, with its value date and the rail it came through
- the demand each receipt cleared, split into current and overdue, under the product’s appropriation order
- prepayments, foreclosures and write-offs, each dated and flagged
Keep reversals and the reporting cut-off with those records. That gives finance a way to reproduce the split and explain a restatement. If the allocation detail is missing, someone has to reconstruct it before the ratio can be checked. If you are choosing that system, NBFC debt recovery and collections software should start from the same demand and receipt records.
What should a collection efficiency report include?
Before you circulate the report, check that another reader can reproduce it:
- Write the period, cohort and formula beside each percentage.
- Reconcile receipts to allocations, with advances and reversals shown separately.
- State how opening overdues and written-off accounts affect the denominator.
- Keep the version of the allocation rule and any restatement with the report.
If you can’t explain the gap between monthly and current efficiency, trace the receipts before drawing a conclusion about collections performance. A consistent percentage can conceal a changing mix of current receipts and older recoveries.
Lokta’s Loan Management records loan demand and receipt allocation on a double-entry ledger. Your reporting definition still needs agreement between finance and collections. If you want to examine that split on your own book, review your collections reporting.
Frequently asked questions
What is the collection efficiency formula?
Express collection efficiency as collections divided by billing, multiplied by 100. There is more than one version. Current collection efficiency divides what was collected against this month's instalments by this month's billing. Monthly collection efficiency, as ICRA defines it, divides all collections in the month, including overdue amounts, by this month's billing. Cumulative collection efficiency divides collections since a start date by billing since that date, sometimes with opening overdues added to the denominator.
Why is collection efficiency above 100%?
Because the formula allows it. When collections of older arrears are added to the numerator but the denominator is only this month's billing, a month in which borrowers catch up on past dues can show more than 100%. That can be a good month, but it can also mean the book is carrying arrears from earlier months. Report current collection efficiency alongside it.
What is X bucket collection efficiency?
For the definition used here, divide receipts allocated during the month to that month's demand from the opening-current cohort by that same cohort's demand for the month, then multiply by 100. Freeze cohort membership at the start. Exclude future dues and receipts from other cohorts, and net reversals using your declared cut-off. Opening-current accounts can have a history of arrears that they have since cleared.
Do prepayments count in collection efficiency?
That is a policy choice, and it should be stated with the number. Including foreclosures and prepayments raises total collections without any change in how borrowers are paying their instalments. Lenders who report to rating agencies or investors should use the definition in the transaction documents and keep prepayments separate where the definition allows.
How do you calculate collection efficiency with an example?
Suppose ₹10 crore falls due in the month, receipts against those dues are ₹9.2 crore and receipts against older arrears are ₹1.3 crore. With advances excluded, current efficiency is 9.2 divided by 10 times 100, or 92%. Monthly efficiency is 10.5 divided by 10 times 100, or 105%. Use the same period and say which receipts each numerator includes.
Sources:
- ICRA, Veritas Finance Limited: Rating reaffirmed for PTCs, 16 October 2025: monthly collection efficiency defined as total current and overdue collections for the month as a percentage of total billing for the month.
- ICRA, Keertana Finserv Limited: Rating action for PTCs, 25 February 2026: cumulative collection efficiency as cumulative current and overdue collections divided by cumulative billing.
- ICRA, Satin Creditcare Network Limited: Rating upgraded for PTC, 27 April 2026 (revised): cumulative collection efficiency with opening overdues added to the denominator.
- ICRA, Rating Methodology: Securitisation Transactions, June 2025: current, monthly and cumulative collection efficiency, and the effect of write-off policy.
- ICRA, Securitisation Transactions rating methodology, July 2019 edition, since superseded: arrears collection efficiency.